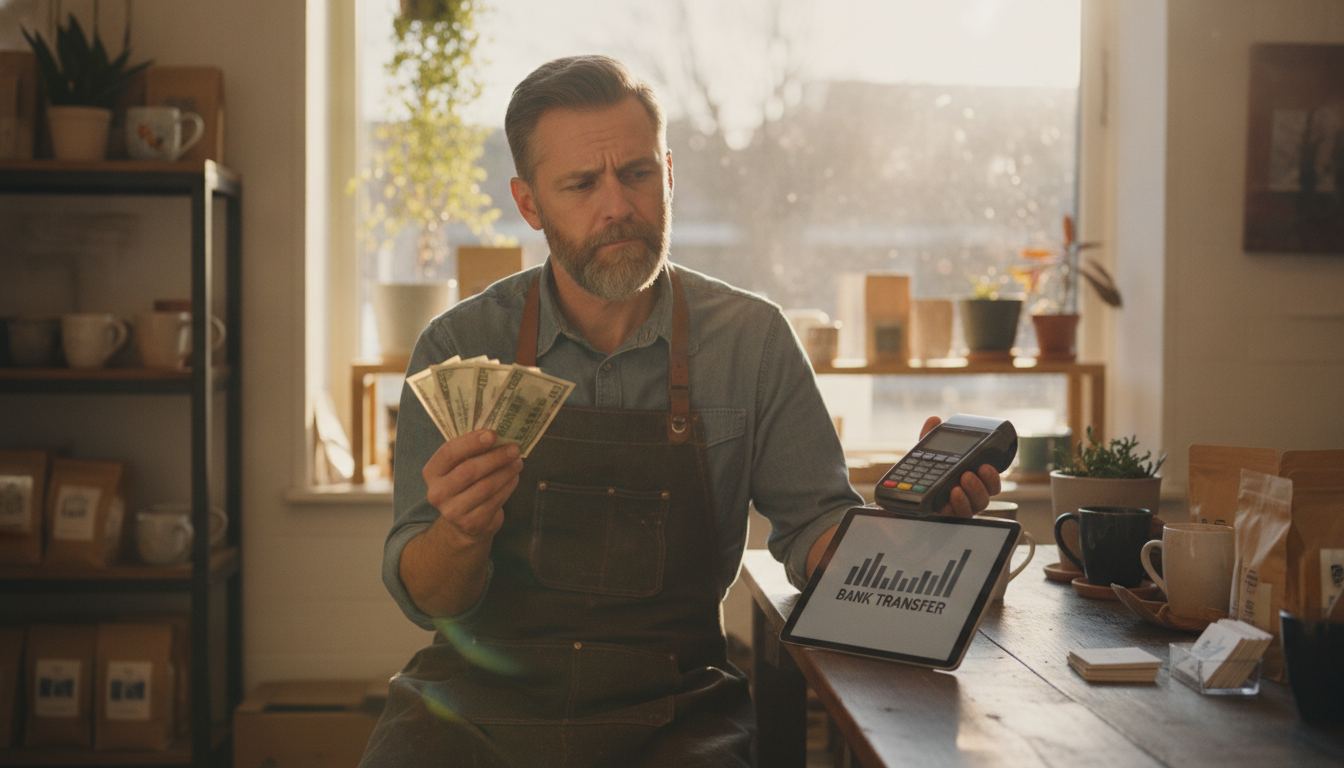
The answer to “what are the three types of payment systems?” is cash based payments, card based payments, and account based payments. This is a practical merchant classification, not a universal rule. A wallet or checkout button often sits on top of a card network or bank transfer rather than creating a separate system.
What are the three types of payment systems?
The three practical groups are distinguished by what carries the value and how the business receives it:
- Cash based payments: The customer gives physical currency directly to the business.
- Card based payments: A credit, debit or prepaid card initiates the transaction through a card network.
- Account based payments: A check or electronic instruction moves money from one financial account to another.
These groups describe the underlying payment rail. They don’t necessarily describe what the customer sees. A digital wallet, payment link or checkout page may send a card payment underneath. A banking app may initiate an account based payment.
This distinction matters when choosing a high-risk payment gateway. The visible checkout experience is only part of the setup. You also need to know which payment rails the gateway supports, where the transaction is sent and which merchant account receives the funds.
How do cash based payment systems work?
Cash based systems settle through a direct exchange between the customer and the business. There is no electronic authorization request, card network or payment gateway involved in that exchange.
Cash can be simple at the point of sale, but the business still needs procedures for counting, storing, recording and depositing it. Those operational steps matter because there is no processor record automatically connecting the payment to a customer order.
For an online business, cash is rarely the main answer. Ecommerce depends on remote payment acceptance, so owners usually need card or account based options. A business comparing those options should separate the payment method from the provider offering it. The method describes how money moves. The provider controls underwriting, account terms and access to the service.
What happens during a card based payment?
A card based payment sends transaction information from the checkout or terminal through the acceptance chain for authorization. The customer’s card issuer decides whether to approve the purchase. The payment is then cleared and settled through the parties supporting the merchant account.
A payment gateway handles the secure passage of transaction data for online acceptance. The gateway is not the merchant account, and neither one is the acquiring bank. A complete setup must connect these parts correctly.
The account structure also matters. An aggregator places many sellers within a shared processing arrangement, while a dedicated merchant account is underwritten for the individual business. Our guide to aggregators and merchant accounts explains why that difference can become important when a business has an unusual product, elevated dispute exposure or a previous processing closure.
Card acceptance creates responsibilities after the sale. Refund practices, customer communication, billing descriptors and dispute records all affect account health. If disputes are rising, address the cause instead of treating each chargeback as an isolated event. This guide explains how to lower your chargeback ratio through practical operational changes.
Where do checks, bank transfers and digital wallets fit?
Checks and bank transfers belong in the account based category because they instruct money to move between financial accounts. The instruction may be written or electronic, but the underlying source is an account rather than physical cash or a card credential.
Digital wallets require a closer look. A wallet is often a customer-facing interface, not a separate payment rail. If the wallet uses a stored card, the transaction is card based. If it draws directly from a financial account, it is account based. The logo or button on the checkout page does not tell you the entire route.
This is why payment method lists can be misleading. A provider may show several checkout choices that ultimately rely on the same underlying system. Ask what rail each choice uses, how refunds are handled and what happens if the primary processing relationship ends.
Which payment system should a high-risk business choose?
A high-risk business usually needs the payment system its customers can use without creating a structure the processor cannot support. For many online merchants, that means card acceptance supported by a properly underwritten merchant account and a compatible gateway.
Underwriting considers the actual business model, not just the preferred checkout experience. Products, fulfillment, marketing, billing practices, dispute exposure and processing history can all affect placement. Our explanation of what payment underwriting examines can help you prepare accurate application materials.
Be direct about previous closures or processing problems. Missing information can delay review or lead to a setup that does not fit the business. If you are preparing to apply, review the merchant account application process before gathering documents. Approval rests with the acquiring bank.
It can also be sensible to consider operational continuity before a problem occurs. A backup merchant account must be legitimate, fully disclosed and independently underwritten. It should never be used to hide activity or route transactions around a provider’s rules.
Frequently asked questions
Is a digital wallet its own payment system?
Usually, a digital wallet is better understood as an interface over another payment system. It may use a stored card, a financial account or a stored balance. Ask which underlying rail funds the transaction. That answer tells you more about authorization, settlement, refunds and disputes than the wallet button alone.
Is a payment gateway the same as a merchant account?
No. A gateway sends transaction information between the checkout and the processing chain. A merchant account is the processing relationship under which the business accepts card payments. They work together, but they serve different purposes. Compatibility matters because a gateway cannot create an approved merchant relationship by itself.
Can a high-risk business accept all payment types?
Possibly, but availability depends on the business model, underwriting and the providers involved. A method displayed by a gateway is not automatically available to every merchant. Describe your products, billing practices, delivery process and processing history accurately so the acquiring bank can evaluate the real activity.
Which payment system costs the least?
There is no universal cheapest choice. Cost depends on the payment rail, transaction pattern, average ticket, business category and provider terms. Operational costs matter too. Cash requires handling, card payments can generate disputes, and account based payments may have different return or reconciliation processes. Compare the whole workflow, not just a headline rate.
What should I do if my current processor closes my account?
Preserve the notice, transaction records, customer communications and fulfillment evidence. Confirm whether refunds, reserves or pending settlements are affected. Then seek a processor that understands the actual business category and disclose the closure during underwriting. Our guide explains what to do after a processor drops you, or you can tell us what happened.